France’s fiscal crisis deepened on Friday as bond markets and street protests intensified pressure on the government ahead of the 2027 presidential election. The 10-year French bond yield surged to 4.8%, nearly double its July level, while the spread over German bunds widened to 1.3 percentage points, signaling investor alarm over Paris’s ability to stabilize its finances. The CAC 40 index has fallen 4% since January, with luxury giant LVMH shedding 40% amid weakening Chinese demand.
The government has yet to present a credible plan to reduce its budget deficit, which reached 5.1% of GDP in 2025 and is projected to rise to 5.7% in 2027, according to the European Commission. France’s debt-to-GDP ratio stands at 115.6%, far exceeding the UK’s 94.3%. Nobel laureate Paul Krugman warned that France may have become “too big to save,” citing unsustainable deficits and rising pension costs as markets treat the country as the “economic sick man of the Western world” .
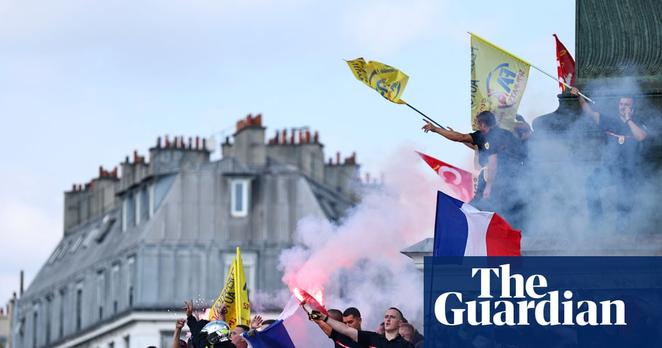
Student protests over education cuts have turned violent, with demonstrations escalating alongside business pessimism. A Medef survey found 82% of firms fear future policy instability, and 66% warned of vulnerability or bankruptcy if political deadlock persists. Finance Minister Roland Lescure has pledged to cut the deficit but has not detailed how. Economist Antonio Fatas said the political and economic climate has pushed France “to the edge of a financial collapse,” with parties exploiting the crisis for electoral gain .
Investors have grown increasingly bearish on French debt. DNCA’s Pascal Gilbert confirmed a short position on French bonds, favoring German debt instead, while Carmignac’s Kevin Thozet cited France’s “very clear budgetary problem” as justification for a similar stance .